Capital Structure · General
What Is a Capital Stack? A Practical Guide for Business Owners
A capital stack shows where a business's money comes from, who gets repaid first and how much risk each funder carries.
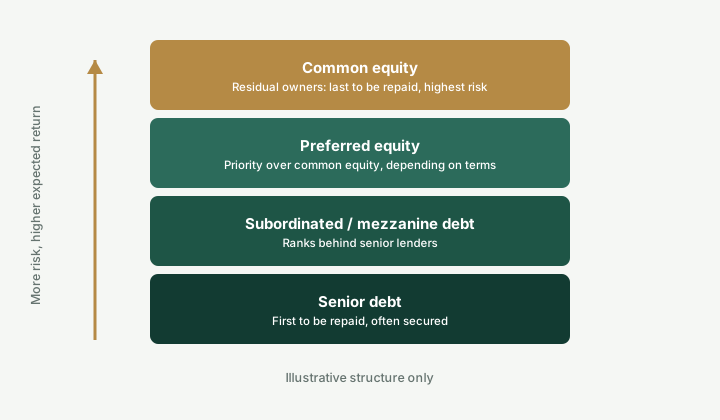
A capital stack is the combination of funding sources a business or project uses to finance its activities. It describes not only where money comes from, but also the order in which different funders are repaid and the level of risk each funding source carries.
A simple business may be funded entirely by the owner's equity and retained profits. A larger company or property project may combine senior loans, subordinated debt, preferred equity and ordinary equity. The exact structure depends on the business, the transaction, the lenders and the investors involved.
Why the capital stack matters
The funding mix affects the cost of capital, repayment obligations, ownership, control and financial risk. Debt can allow owners to keep ownership, but it creates scheduled repayment obligations. Equity may reduce immediate repayment pressure, but it can dilute ownership and influence. More junior funding often carries higher risk and may require a higher return.
The common layers
| Layer | Repayment priority | What to know |
|---|---|---|
| Senior debt | First | Often secured on assets and supported by covenants. Usually the cheapest layer. |
| Subordinated or mezzanine debt | After senior lenders | Higher risk to the lender, so it generally costs more. |
| Preferred equity | Before common equity | May have priority for distributions or liquidation proceeds, depending on its terms. |
| Common equity | Last | The residual ownership layer, which absorbs losses after more senior claims. |
A simplified example
Imagine a project that needs $1 million. It might be funded with $500,000 of senior debt, $150,000 of subordinated debt and $350,000 of equity. That is 50%, 15% and 35% of the stack. This is only an illustrative structure, not a recommendation. Actual terms, security, priority, fees and legal rights must be reviewed in the governing documents.
Questions to ask before you choose a structure
- What is the total funding requirement?
- What cash flow will service the debt, and how does the debt service coverage ratio look?
- What collateral is available, and are personal guarantees involved?
- How much ownership dilution is acceptable?
- What happens if revenue falls?
- What is the repayment order if the business is sold or liquidated?
The key lesson is that the cheapest headline interest rate does not automatically make a funding structure best. Compare total cost, repayment flexibility, control, security, risk and resilience under downside scenarios. Read our guide to debt versus equity financing next, and use the loan repayment calculator to test the numbers. For complex transactions, obtain qualified legal and financial advice.
Frequently asked questions
Is a capital stack only for property or large deals?
No. Any business has a capital stack, even a simple one funded by the owner's equity and retained profit. The idea becomes more visible as debt and outside investors are added.
What is mezzanine debt?
It is debt that ranks behind senior loans but ahead of equity. Because it carries more risk than senior debt, it generally costs more.
Sources
- US Small Business Administration: Loans, US Small Business Administration
- US Small Business Administration: Manage your finances, US Small Business Administration
- IRS: Small Business and Self-Employed Tax Center, Internal Revenue Service
Educational information only, not individual financial, tax, legal or accounting advice. Read the disclaimer.
Discussion (0)
No comments yet. Be the first to add a question or a practical experience.